Still on the Fence? Your Mortgage Rate Hold Has an Expiry Date
Wednesday, Oct 28, 2026
Still on the Fence? Your Mortgage Rate Hold Has an Expiry Date
What the October 28, 2026 interest rate announcement means for Kawartha Lakes buyers and homeowners
By Jami Joy | Team Joy
If buying a home has been sitting on your “maybe soon” list, it’s time to take another look at your mortgage pre-approval.
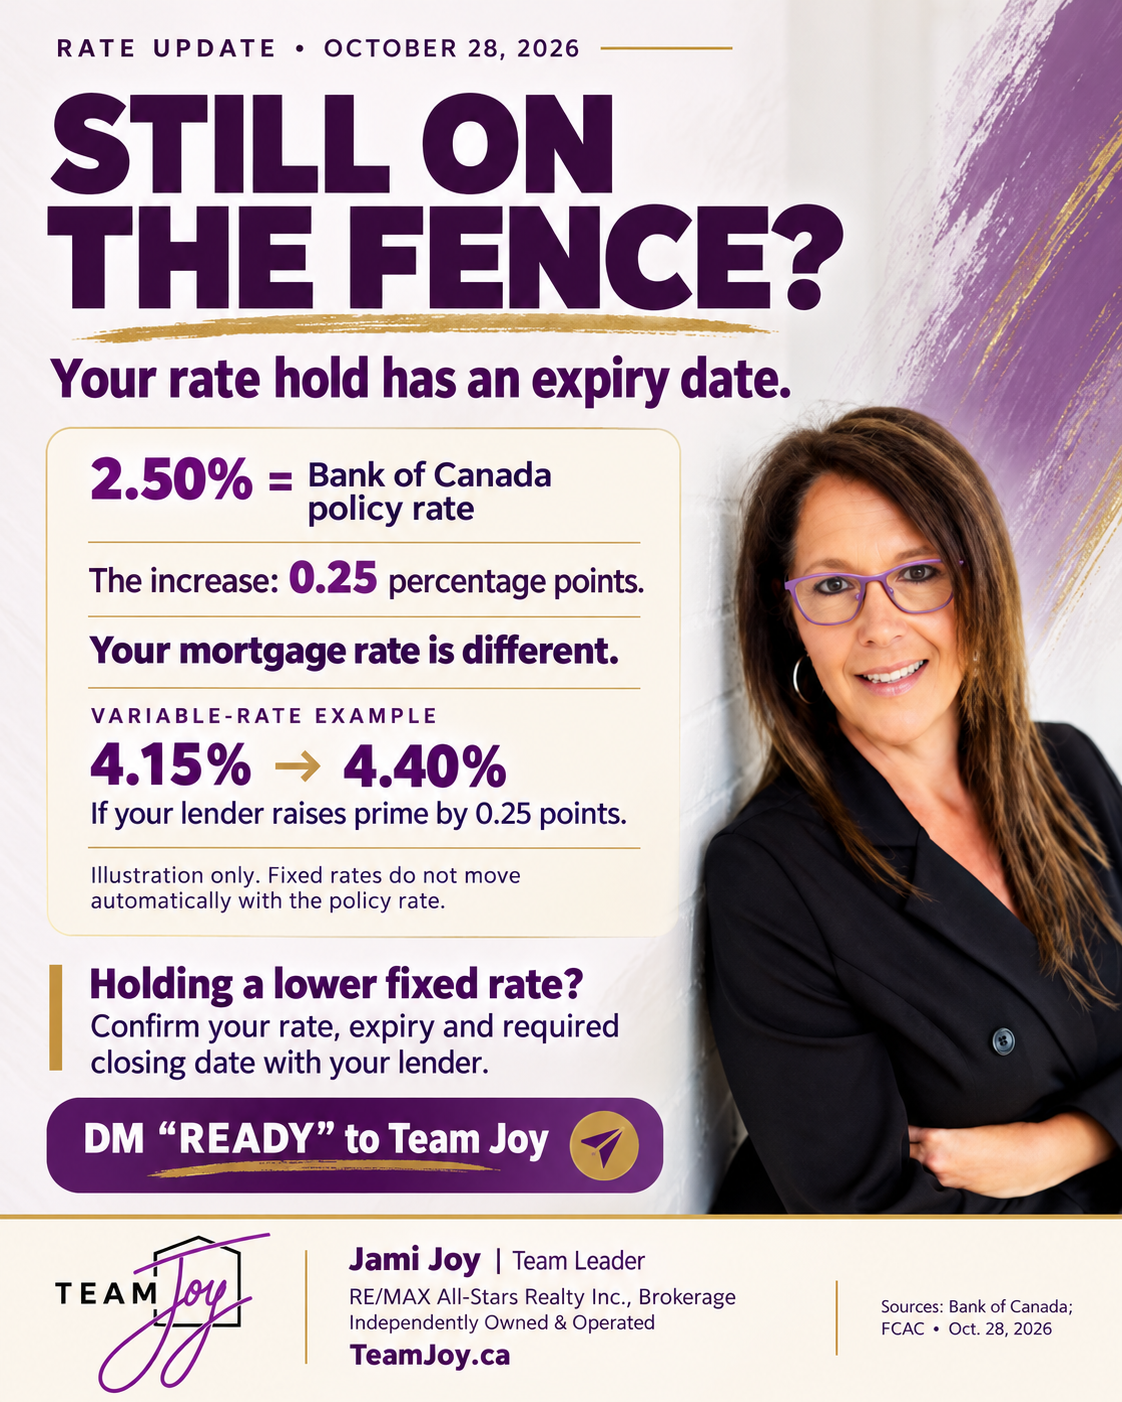
On October 28, the Bank of Canada raised its policy interest rate from 2.25% to 2.50%.
But before that headline sends you down a mortgage rabbit hole, let’s explain what it actually means—and why buyers holding an earlier fixed rate should check their paperwork.
Is 2.50% the mortgage rate I’ll pay?
No. The Bank of Canada’s policy rate and your mortgage rate are different numbers.
The increase was 0.25 percentage points, also called 25 basis points. It wasn’t a 2.5% increase.
Your mortgage rate is set by your lender and depends on the mortgage you choose and your qualifications.
For a real-world reference, when checked on October 28, RBC’s website displayed select special offers of 4.99% for a three-year fixed mortgage and 5.14% for a five-year fixed mortgage.
Those are advertised examples with eligibility requirements, not quotes for every buyer. Lender pricing can change, and a displayed rate may not yet reflect the latest announcement. Ask your mortgage professional for a current quote.
What happens if I have a variable-rate mortgage?
Variable mortgage rates are generally tied to your lender’s prime rate.
For example, if your rate is 4.15% and your lender increases prime by 0.25 percentage points, your rate would rise to 4.40%, assuming your contractual discount stays the same.
That is an illustration, not a confirmed new rate.
Depending on your mortgage, your payment may increase, or more of your existing payment may go toward interest instead of reducing your balance.
What if my mortgage is fixed?
An existing fixed mortgage rate stays the same for the remainder of its term.
When that term ends, your renewal rate may be different. If renewal is approaching, ask for your options early so you can plan around the payment.
Already pre-approved? Check your rate hold.
This is where buyers sitting on the fence should pay attention.
If you have a valid fixed-rate hold below what your lender currently offers, you may still be able to use that earlier rate.
But a pre-approval is not a guarantee of final financing, and a variable-rate pre-approval should not be assumed to lock the interest rate itself.
Ask your lender or mortgage broker:
-
What rate and mortgage product have I actually secured?
-
When does my rate hold expire?
-
By what date must my purchase close to use it?
-
What conditions must I meet?
-
What payment should I budget for?
Get those answers before planning your purchase around an older quote.
Does that mean I should buy immediately?
A rate hold is a reason to get organized—not a reason to buy a home you cannot comfortably afford.
If purchasing already fits your finances and plans, confirming a favourable rate hold can help you make a more informed decision about timing.
At Team Joy, we can help you focus your Kawartha Lakes home search, compare properties and coordinate your purchase timeline with the financing information your lender provides.
The fence might be comfortable. It won’t extend your rate hold.
Ready to find out what your next move could look like? Contact Team Joy through TeamJoy.ca, and let’s put a practical plan together.
Jami Joy | Team Leader
Team Joy
RE/MAX All-Stars Realty Inc., Brokerage
Independently Owned & Operated
Information checked October 28, 2026. Rates and lender conditions can change. Mortgage examples are for education only; confirm your financing, eligibility and deadlines with your lender or licensed mortgage broker.
Sources: Bank of Canada, “Policy interest rate”; Financial Consumer Agency of Canada, “Interest on mortgages” and “Getting preapproved for a mortgage”; RBC Royal Bank, “Current Mortgage Rates.”